Traditional private medical insurance vs Equipsme
Many private health insurance plans come with some form of underwriting for pre-existing conditions. The whole principal of insurance is about protection against the unexpected – rather than ‘expected’ risks. Exclusions exist to protect insurance companies from risks, and large claims. But they also work for companies, and individuals. Exclusions can help keep premium costs down, by managing the number and size of claims, and reducing the need for additional increases to be passed on to employers through higher premiums - or to the employees via P11D tax.
Equipsme’s approach to underwriting
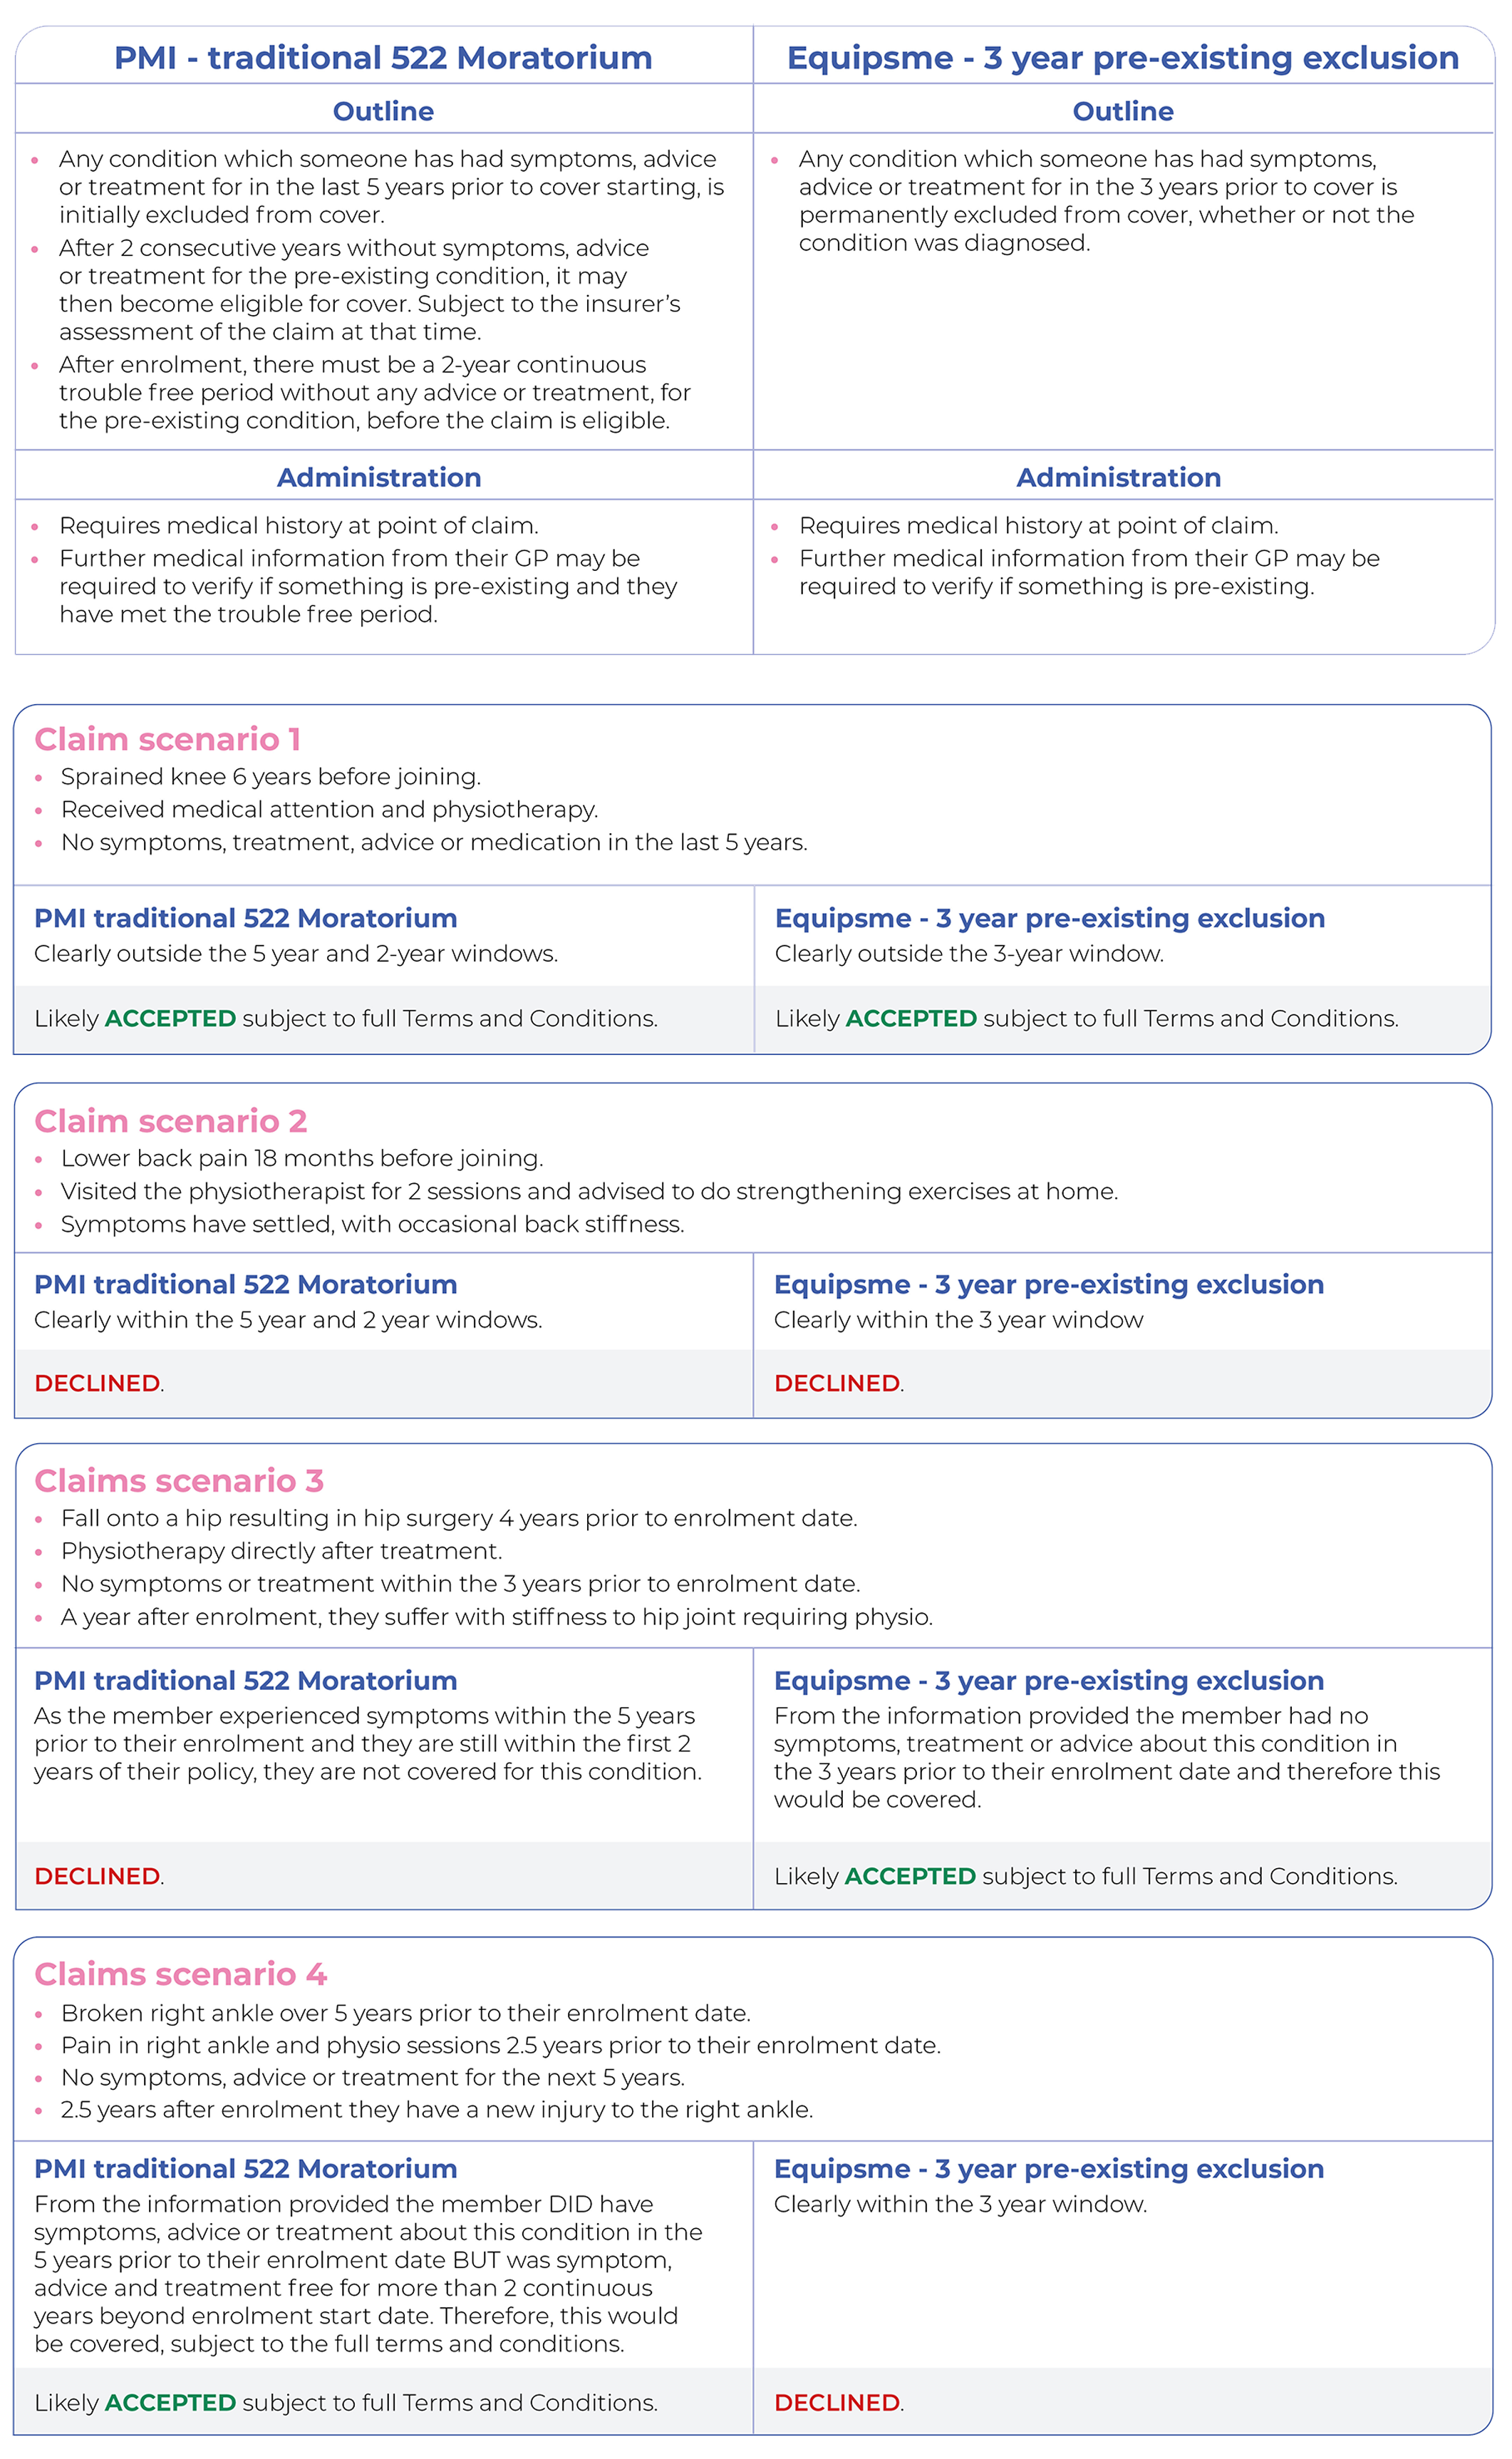
Equipsme’s approach to pre-existing conditions is slightly different to other private health insurance providers, but in our opinion, is easier to understand. We don’t need medical information up front, just a simple online declaration. Equipsme has an underwriting exclusion which will not cover any disease, illness or injury where in the three years before the start of the insurance cover, a member has experienced symptoms or received medication, advice or treatment; whether or not the condition was diagnosed.
Different approach, often a similar outcome
The underwriting rules are different, but in practice the outcome for an individual claim may be the same under either approach. There will be scenarios where traditional 522 moratorium underwriting is more favourable, and others where Equipsme’s 3-year pre-existing exclusion is more favourable. The examples below help bring those differences to life.
Download the guide here
Terms and conditions apply: Such as the exclusion of pre-existing conditions for Physiotherapy, Diagnosis and Treatment and the exclusion of cancer treatment. Find out more here: www.equipsme.com/our-health-insurance-plans
Contact us: Speak to your usual BDM contact or email us at [email protected]